InsurTech PR for the companies changing how insurance works
We help insurance technology companies explain complex products, earn relevant coverage, and build credibility with carriers, brokers, underwriters, and investors.

Who We Work With
Built for insurance technology companies
Whether you help insurers assess risk, manage claims, or prevent losses, we make the value clear to the people who need to understand it.
- 01
Underwriting and risk analytics
- 02
Claims technology and automation
- 03
Insurance platforms and distribution
- 04
Connected devices and loss prevention

Who We Are
Founder-led InsurTech PR
I’m Justin, founder of Salient.
20 years in PR. I lead every partnership personally, from strategy through execution.
Our Service
PR services for insurance technology companies
From product launches to ongoing media outreach, we build stories around the problems your technology solves and the evidence behind it.
Our Work
Insurance technology, explained through real-world results
Brickeye
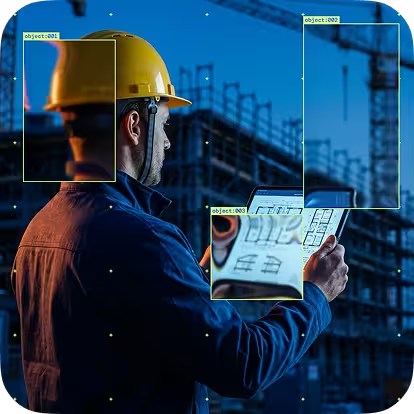
Brickeye came to us with a $10M Series B. We turned its story about automated water-damage prevention into an Engineering News-Record exclusive, connecting the technology to the builders’ risk challenges facing contractors, developers, and insurers.
Alex Fuentes
EVP Strategic Growth and Business Development at Brickeye
Salient PR found the story we didn’t know we had. We came to them with a funding announcement. They turned it into an industry narrative—and put us in front of the buyers who matter.

Brickeye
Brickeye came to us with a $10M Series B. We turned its story about automated water-damage prevention into an Engineering News-Record exclusive, connecting the technology to the builders’ risk challenges facing contractors, developers, and insurers.
With Salient PR
Make your technology easier to understand and your evidence harder to overlook, with PR aimed at the people who evaluate, buy, and fund insurance solutions.
- 01
Reach relevant insurance, technology, and business media
- 02
Build credibility with carriers, brokers, and underwriters
- 03
Explain your product’s value with real customer evidence
- 04
Support launches, partnerships, and funding announcements
- 05
Establish your leaders as informed voices in insurance technology
Salient PR found the story we didn’t know we had. We came to them with a funding announcement. They turned it into an industry narrative—and put us in front of the buyers who matter.
Our Approach
How we approach InsurTech PR
Insurance Audiences
Different buyers ask different questions. We tailor the story for carriers, brokers, underwriters, and the customers they serve.
Evidence First
We build stories around product capabilities, customer experience, and results your team can substantiate.
Specialist Support
We bring in specialist research, writing, and search expertise when your campaign needs it.
Founder-Led
Justin leads the strategy and execution, so the person you hire stays involved in the work.
Clear Reporting
You see the pitches, media lists, responses, and coverage. You know what is happening and why.
Practical Stories
We connect the technology to a real problem: a prevented loss, a smoother claim, or a better way to assess risk.
AI Intelligence Layer
We monitor relevant news and match it to your company’s expertise, so timely opportunities do not pass unnoticed.
Focused Execution
We agree on priorities, gather the evidence, and start outreach with a clear story and the right targets.
Common questions about InsurTech PR
What to know before we work together.
What does an insurtech PR agency do?
It earns coverage for insurance technology companies in the places that shape buying: the insurance trade press read by carriers, brokers, and underwriters, the vertical press where the risk actually sits, and the business press when the story is big enough to leave the category. That means media relations, executive visibility, data campaigns built on your own claims and loss numbers, and the customer references that make any of it credible. It is not advertising, and it is not demand generation. It is the third-party proof those things lean on.
Should an insurtech company hire a fintech PR agency or an insurance specialist?
It depends on who has to believe you. Fintech and insurtech share investors and much of the same business press, so a fintech agency will get you funding coverage. What it usually cannot do is reach carriers, brokers, and underwriters, who read their own trade press and judge claims against loss ratios rather than growth rates. If your buyer sits inside an insurance company, the insurance half of the media list is the part that decides whether the program works, and it is the half most tech agencies do not have.
Which publications actually cover insurtech?
Two groups. The insurance trade press reaches the people who price and sell risk: Insurance Journal, Digital Insurance, Insurance Business, Carrier Management, Business Insurance, PropertyCasualty360, Coverager and Reinsurance News. Then the vertical press where the risk sits, which for construction insurance means Engineering News-Record and the contractor titles. Business and tech media cover insurtech when the story stops being about insurance, which is worth planning for but not worth planning around.
Can you handle regulatory and compliance communications for insurers?
Yes, and in this category the constraint tends to improve the work. Reporters covering insurance read policy language for a living and will ask what a loss reduction figure is measured against. Anything touching pricing, coverage or underwriting outcomes has to be defensible and usually needs carrier or legal sign-off before it goes out. We build that into the process rather than around it, because a claim you can stand behind travels further than a bolder one you have to walk back.
Can you get coverage without a funding announcement?
Yes, and in insurance it is often the better route. Brickeye had a $10M Series B, which is not a number that earns tier-one coverage on its own. We led instead on the fact that water damage is the largest insurance claim in construction and on a single scene: a 40-story tower at 2am, a ruptured line, nobody on site, the system shutting it off in 45 seconds before the water could flood the site. Engineering News-Record ran it as a trend piece rather than a funding item, and it carried into TechCrunch StrictlyVC and The Logic, then national syndication.
Who will run the account day to day?
Justin, who founded the agency and has twenty years in PR. He leads every partnership from strategy through execution, supported by senior people and a network of specialists brought in when a project needs them. There is no hand-off after the pitch, which is the single most common complaint about agencies and the reason half our clients came to us from one. Our average client relationship runs twenty-seven months.
What does it cost, and how soon does it work?
Most engagements run between $10K and $20K a month, with $15K typical, on a six month minimum. What moves it is scope: how many announcements are in the year, how many executives we are positioning, whether analyst relations is included. On timing, expect first placements in sixty to ninety days. Month one can look quiet even when it is working, because reporters often take a week or more to reply.
Ready?
Let’s talk InsurTech
Tell us what you’re building and who needs to understand it. We’ll help you turn the technology into a clear, credible story.